Blog · 2026-10-28
The Fed Held Rates. Here's Why Your Mortgage Rate Didn't Budge
Shopping for a home in Rhode Island this fall? Today's Federal Reserve meeting is worth five minutes of your time, but probably not for the reason you think.
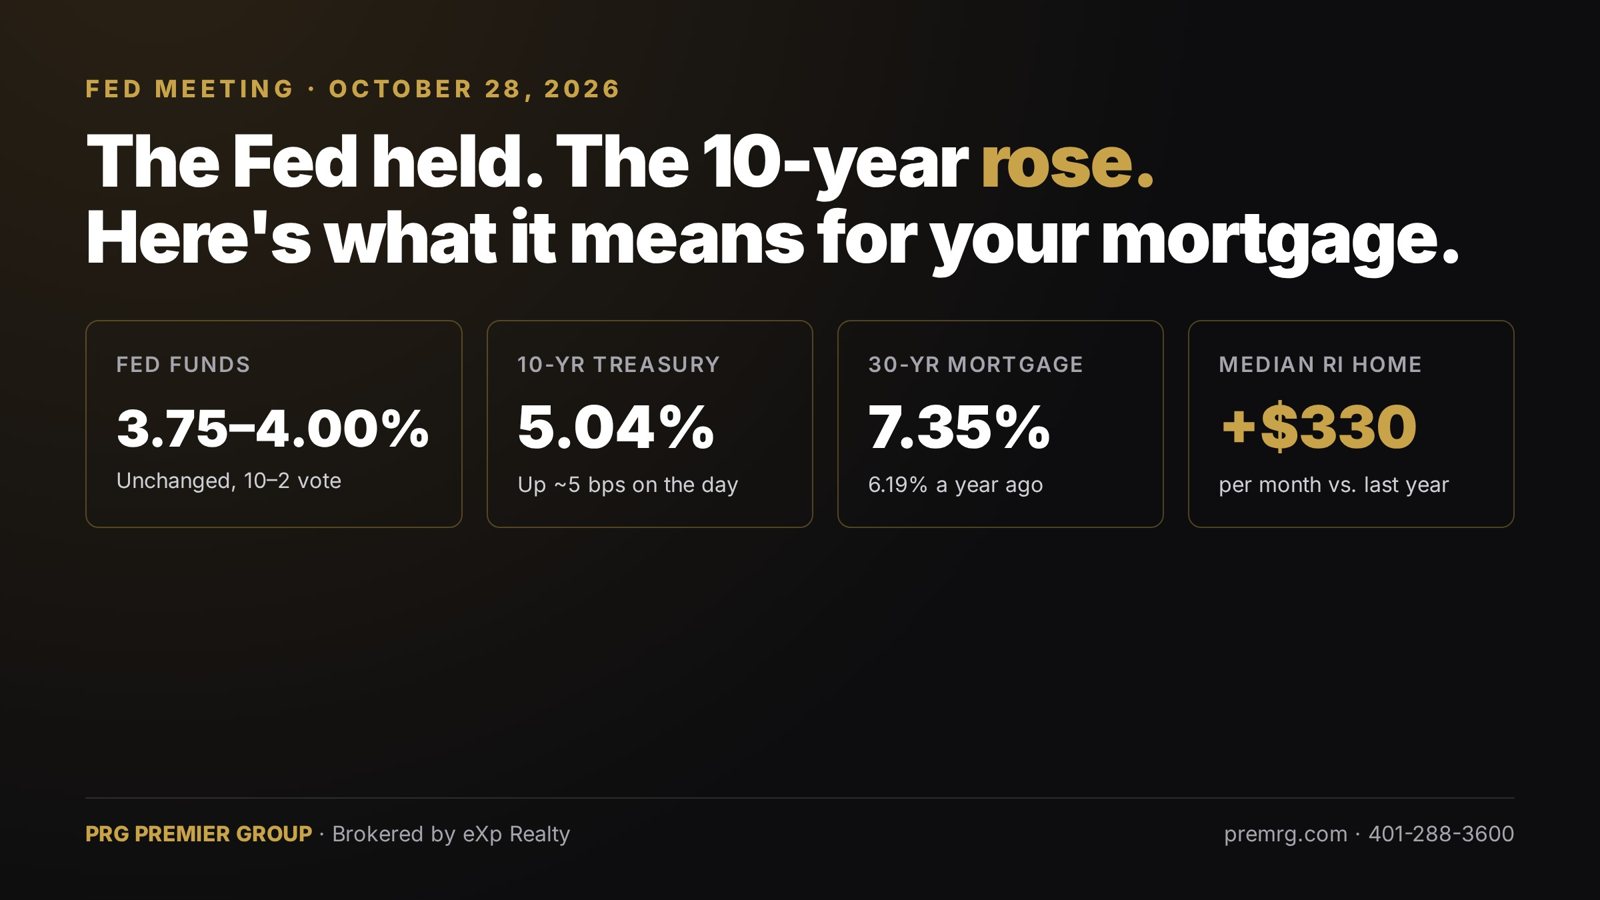
The Fed kept its key rate unchanged on October 28, in a range of 3.75% to 4.00%. It raised that rate a quarter point in September, the first increase since 2023, and two of the twelve voting members wanted to raise it again today. So rates aren't coming down any time soon from the Fed's side. But the Fed's rate is not your mortgage rate.
Why the 10-year Treasury is the number to watch
The Fed sets an overnight rate between banks. Your 30-year fixed mortgage is priced off something else: the yield on the 10-year U.S. Treasury note. Investors who buy mortgage bonds compare them to the 10-year because most mortgages get paid off or refinanced within about a decade. Lenders take the 10-year yield and add a margin on top.
That's why the two can move in opposite directions. This afternoon the 2-year Treasury, which follows the Fed closely, eased to about 4.72%. The 10-year rose about five basis points and closed near 5.04%. Investors are still worried about inflation over the long run, with oil above $100 a barrel, and they want to be paid more to lend for ten years.
Mortgage News Daily reported the Fed announcement itself had no impact on mortgage rates today. Its 30-year index sits at 7.35%. Freddie Mac's weekly average was 7.32% last week, compared with 6.19% a year ago.
What a full point does to your payment
Take a home at Rhode Island's September single-family median of $534,000 and put 20% down. The loan is $427,200.
- At 6.19% (a year ago): about $2,614 a month in principal and interest.
- At 7.35% (today): about $2,943 a month.
- Difference: roughly $330 a month, or nearly $4,000 a year.
Put another way, the monthly payment that covered a $427,200 loan last year now covers about $379,000. If your budget is fixed, your price range has shifted down.
A buyer's game plan for higher rates
- Get pre-approved at today's rate, not last year's. Know your real number before you fall in love with a house.
- Track the 10-year. When it drops, rates usually follow within a day. Have your lender ready to lock.
- Negotiate for a buydown. Purchase applications are still 18% below a year ago, per the Mortgage Bankers Association. Fewer buyers means sellers are more open to credits. A seller-paid buydown can lower your rate and payment more than the same dollars off the price.
- Understand ARMs before you use one. They're 11.3% of applications now, the highest in over a year. Know the reset date, the caps and the worst-case payment.
- Plan to refinance, don't count on it. Buy a payment you can live with today. If rates fall later, a refinance is a bonus.
What could change from here
New inflation data (the PCE index) and third-quarter GDP come out tomorrow, and the next Fed meeting is December 9. Hotter inflation would push the 10-year and mortgage rates higher. Softer numbers could bring some relief. Right now mortgage rates are running about 2.3 points above the 10-year, wider than the long-run norm of around 1.7, so there is room for rates to improve if markets calm down.
Bottom line
- The Fed held steady today and is leaning toward hiking, not cutting.
- Your mortgage rate follows the 10-year Treasury, now about 5.04%.
- Rates near 7.3% add about $330 a month on a median-priced RI home versus a year ago.
- Less competition gives you room to negotiate. Use it.
Want to see what you can comfortably afford in your target town? Search every Rhode Island listing on this site, or call 401-288-3600 to talk with a local agent.
Sources: Federal Reserve FOMC statement, October 28, 2026; CNBC and InvestingLive Treasury closes, October 28, 2026; Freddie Mac PMMS, October 22, 2026; Mortgage News Daily, October 28, 2026; Mortgage Bankers Association via CNBC, October 28, 2026; RI Association of Realtors / State-Wide MLS, September 2026. Payments are principal and interest only, illustrative, not a loan quote. Information deemed reliable but not guaranteed. Equal Housing Opportunity.